All Categories
Featured

Essential Final Expense or Burial Insurance for Seniors
Table of Contents
How does the 2026 subsidy cliff impact Pennsylvania household health insurance coverage? The return of the 400 percent FPL aid cliff in 2026 around $128,600 annual income for a household of four substantially increased expenses for middle-income Pennsylvania families on Pennie.
Even households above the APTC threshold may have children eligible for CHIP if family income is listed below 319 percent FPL per-child, considerably minimizing total family coverage cost. Can Pennsylvania households register in CHIP outside of open registration? Yes. Pennsylvania CHIP enrollment is open year-round there is no open registration duration limitation for CHIP or Medical Help.
Children who gain eligibility due to earnings changes, loss of other coverage, or other scenarios can be enrolled in CHIP at any point throughout the year. CHIP, Medical Help, and Pennie market plans often interact for Pennsylvania families.'s certified PA brokers confirm eligibility for each family member and complete registration at no extra cost.
is not affiliated with Pennie, the Pennsylvania Department of Human Services, the Pennsylvania Insurance Coverage Department, or any provider consisting of CHIP providers. The agency assists Pennsylvania citizens compare strategies and enlist in coverage at no extra cost.
An insurance coverage program jointly moneyed by states and the federal government that offers health insurance coverage to low-income children and, in some states, pregnant ladies in households who earn too much earnings to get approved for Medicaid but can not manage to acquire personal medical insurance protection.
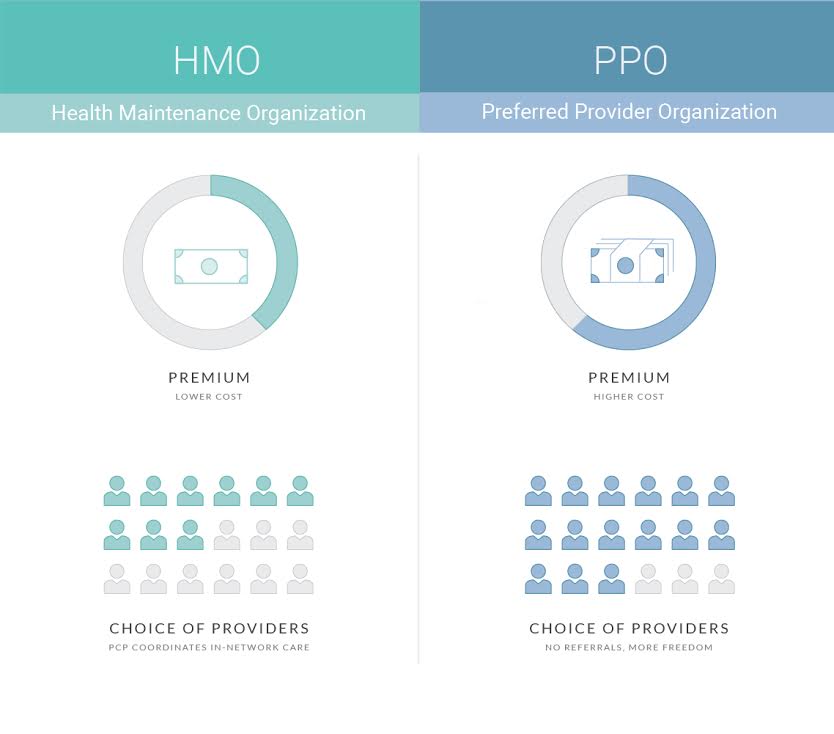
Medicare in FullertonComparing PPO Vs HMO Plans
We learned the other day that the average cost of a household medical insurance policy through a company reached almost $27,000 this year, 6% greater than what it cost in 2024. As if that weren't alarming enough, researchers are anticipating that the overall likely will skyrocket toward $30,000 next year due to the fact that of rising medical expenses and the relentless pressure insurance companies are under from Wall Street to increase their profits.
Despite duplicated guarantees from insurance providers that we can count on them to hold down the cost of healthcare and consequently the premiums they charge there are now numerous years of proof from scientists like KFF, which tracks annual modifications in employer-sponsored coverage that they have not and can not deliver on their guarantees.
A medical insurance policy today is normally less important than it was a decade ago since families have to spend more and more cash out of their own pockets every year before their protection kicks in. In addition, they are far more likely to be notified that their insurers will not cover the care their doctors state they require.

That is a rate of boost much greater than basic inflation and also greater than medical inflation. Not just has the overall cost of an employer-sponsored plan skyrocketed, so has the share of premiums employees should pay. This year, companies subtracted an average of $6,850 from their workers' paychecks for household coverage, up from $4,823 in 2014, a 42% boost.
Medicare in FullertonThe Affordable Care Act, to its credit, set up a cap on out-of-pocket expenses in 2014, however that cap has been increasing each year together with premiums. (The U.S. Department of Health & Human Services sets the out-of-pocket max every year, pegging it to the average boost in premiums.)In 2014 the out-of-pocket cap for a family policy was $12,700.
Optimizing Medicare Part D Coverage in 2026
And remember that the cap just applies to in-network care. If you go out of your insurer's network or take a medication not covered under your policy, you can be on the hook for hundreds or thousands more. While many employer-sponsored strategies have caps that are significantly lower, many people and households reach the legal max every year.
Insurance companies stated their 2024 earnings were somewhat depressed because more of their health strategy enrollees went to the doctor and picked up their prescriptions last year. Financiers were furious that insurance providers couldn't keep that from happening, as you'll see in the charts below.
But in general, the stock rates of the big insurance coverage conglomerates have increased gradually for many years as we and our companies have actually had to invest more for policies that cover less. UnitedHealth Group, the greatest of the 7, saw its stock rate boost 483% between 2014 and 2024 from $85.31 a share on Dec.
Choosing Top Medicare Supplement Policies in 2026
31, 2024. The majority of the other companies saw similar growth in their shares over that time period. By contrast, the Dow Jones Industrial Average increased 139% (from $17,823.07 to $42,544.22), and the S&P 500 increased 186% (from $2,058.90 to $5,881.63) throughout the very same period. Back to those premiums and out-of-pocket requirements.

Table of Contents
Latest Posts

Understanding Universal Life IUL Policies for Retirement
Optimizing Indexed Universal Life Growth Benefits for Retirement
Essential Final Expense or Burial Insurance for Seniors
Latest Posts
Understanding Universal Life IUL Policies for Retirement
Optimizing Indexed Universal Life Growth Benefits for Retirement
Essential Final Expense or Burial Insurance for Seniors